

Inter Banking & Money Transfer
by Banco Inter SA
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 100.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
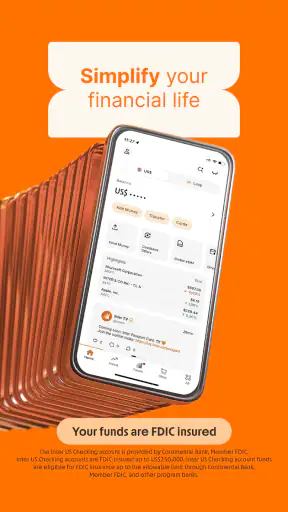
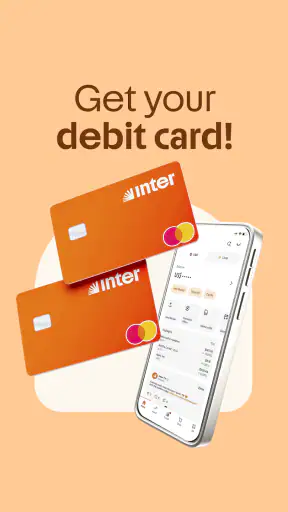
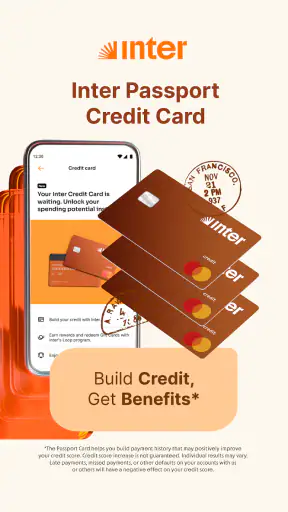
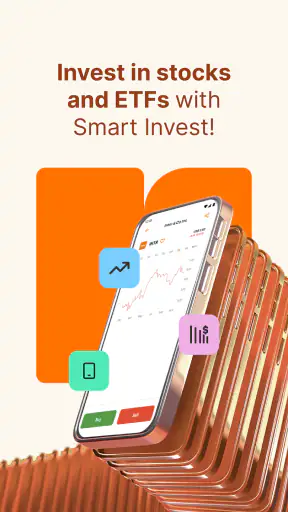
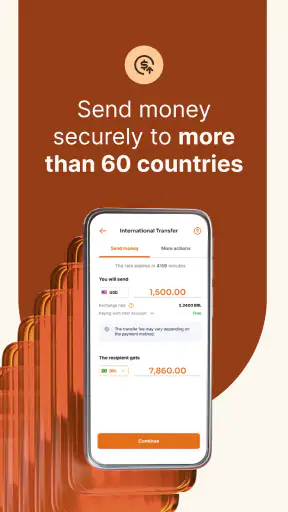
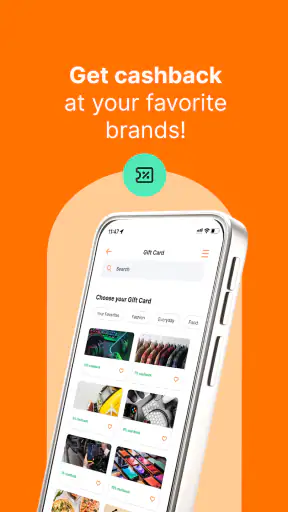
 Analysis by Getfullapps
Choosing a banking app is less about finding the longest feature list and more about finding one that fits the way you already handle money. I look at three things first: whether everyday banking is gathered in one place, whether transfers are practical for the people I actually need to pay, and whether the app remains understandable when a financial task becomes more complicated. Inter Banking & Money Transfer is aimed at people who want a broad digital banking experience rather than a separate app for every financial job.
Developed by Banco Inter SA, this free finance app combines digital banking with gift cards and international money transfers. That combination gives it a wider scope than a simple account app, while still keeping the experience centered on a mobile device. In my use, the main appeal is not one isolated tool. It is the possibility of organizing several money-related tasks around one account and one familiar interface.
The app has a 4.4 average rating from around 4.9 million ratings, and it has passed 100 million installs. Those figures suggest that it is not a niche experiment, but popularity should not decide the choice by itself. A banking app can be widely used and still be a poor match for someone who needs a very specific local service, a highly specialized investment platform, or a different international transfer arrangement.
What I would check before moving my banking routine
My first decision criterion is coverage. If I only need to check a balance or make an occasional transfer, a traditional bank’s app may already be enough. Inter becomes more interesting when I want banking, gift-card purchases, and international money movement available from the same digital home. That breadth can reduce the need to jump between services, but it also means there are more areas to understand before I make it my main financial tool.
The second criterion is the kind of transfer I make. A domestic transfer between people I know is a different job from sending money across borders. I would not judge both workflows by the same standard. For local payments, speed and a clear confirmation screen matter most. For international transfers, I care more about recipient details, currency handling, the final amount received, and the point at which a transaction can no longer be changed. Anyone considering the app should test the path that matches their real life, not just browse the home screen.
The third criterion is comfort with a digital-first relationship. Inter is designed for people who are happy to manage financial tasks through an app. That can feel efficient if I prefer self-service, but it may feel limiting if I regularly need face-to-face help or want a branch employee to explain a complicated issue. The right question is not whether digital banking is modern; it is whether I am comfortable taking responsibility for reviewing details before confirming a transaction.
I would also consider how much switching effort I am willing to accept. Moving a banking routine means updating payment habits, learning where important actions live, and making sure recurring obligations are not forgotten. The app is free, which removes one obvious barrier, but free access does not eliminate the practical work of changing accounts. I would start with a small, low-risk task and only expand my routine after the navigation feels natural.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The everyday situation where it makes sense
Imagine I am preparing for a weekend away. I need to manage money in my account, send a transfer to a family member, buy a gift card, and arrange an international transfer for someone abroad. With separate providers, each task may require a different login, a different security check, and a different transaction history. Inter’s strongest idea is putting these needs in one banking environment.
That does not mean every task becomes effortless. It means I have fewer places to remember and fewer apps to keep updated. I would still pause before sending money internationally, check the recipient information carefully, and save the confirmation details. The convenience comes from centralization, not from removing the need for attention.
Where the all-in-one approach wins
The clearest strength is the range of jobs covered by one app. A basic banking app may handle account activity and transfers well but leave gift cards or international money movement to other services. A dedicated transfer service may be excellent for one corridor or one type of payment but offer little help with broader banking. Inter sits between those categories, which is useful for someone who values a single starting point.
I also like the practical advantage of having a consistent place to begin. When I want to check whether money has arrived, start a transfer, or look for a gift-card option, I do not have to remember which specialist app handles which task. That sounds minor until a payment is time-sensitive or I am using a phone with limited storage and attention. The real benefit is reduced app-hopping, not a promise that every financial task is automatically simpler.
Gift cards are another area where the combined model can be convenient. I can see why this would appeal to someone who buys them regularly for family, personal spending, or a planned occasion. The trade-off is that I would want to compare the available choices and the final transaction details with the usual retailer or specialist option before assuming the in-app route is always the best value or most flexible.
International transfers give the app a broader role than a purely domestic banking tool. For a user who occasionally sends money abroad, having that function close to everyday banking may be easier than opening a separate account. I would treat the feature as a workflow advantage rather than assume it replaces every specialist remittance service. The best choice can depend on the destination, the recipient’s needs, and how often the transfer is made.
Small habits that make the experience safer and clearer
One useful habit is to separate checking from confirming. I would first enter the recipient and amount, then review the complete summary before authorizing anything. This is especially important when switching between a normal transfer and an international one, because the purpose and details of the transaction can differ even when the screens look familiar.
A second habit is to treat gift-card purchases as spending decisions, not just banking actions. I would confirm the recipient, the intended value, and the delivery or redemption details before completing the purchase. Keeping the confirmation visible until the recipient has what they need is sensible, particularly when the card is being bought for someone else.
A third practical tip is to use the app as a central dashboard without making it the only record I trust. For important transfers, I would keep the confirmation information and reconcile the movement with my own budget. This makes it easier to notice a mistaken amount or an unexpected transaction instead of relying on memory after several different financial actions.
I would also explore the app gradually. Rather than moving every financial responsibility on the first day, I would begin with balance checking or a familiar domestic transfer. Once I knew how confirmations, history, and support paths worked, I would consider gift cards or international transfers. This staged approach lowers the cost of a mistake and gives me a realistic sense of whether the interface suits my habits.
Where another type of service may fit better
An all-in-one app is not automatically the best option for everyone. If my priority is a highly focused international remittance experience, I might prefer a specialist service that is built around that single job. A specialist may make the transfer path feel more direct for frequent users, while Inter’s broader banking context could feel like extra navigation. I would compare the actual destination and recipient workflow rather than choose based only on the word “international.”
If I mainly want traditional bank support, a bank with a strong branch network or a service model built around personal assistance may be a better fit. Inter is most appealing when I am comfortable doing the work digitally. Someone who expects regular in-person explanations, paper-heavy processes, or a familiar local branch should not switch simply because the app gathers more features together.
There is also a trade-off between breadth and focus. More functions can make an app more useful, but they can also make the interface feel busier. A person who only wants a clean way to view transactions may find an all-in-one financial hub more than necessary. In that case, a simpler banking app could be easier to learn and less distracting.
People who already have a trusted setup may see little reason to move. If my current bank handles domestic payments smoothly and I rarely buy gift cards or send money abroad, Inter’s wider range may not justify changing routines. The app has to solve a real inconvenience, not merely offer more buttons. I would switch because the combined workflow saves me time or simplifies a recurring task, not because a large install base makes the decision for me.
Another consideration is device compatibility and maintenance. The current version is 26.15.1, and the app requires Android 7.0 or later. That is helpful for many Android users, but anyone with an older device should check compatibility before planning a move. I would also keep the app updated and make sure my phone itself is protected, because mobile banking depends on the security of the whole device, not just the application.
What switching actually involves
The cost of switching is mostly organizational. I would need to learn the layout, update the places where I receive or send money, and decide which transactions should remain with my existing provider during the transition. I would not close an old account immediately. Keeping a short overlap gives me time to confirm that salary payments, recurring bills, and important contacts are handled correctly.
I would prepare a simple checklist before moving anything important: regular payments, people I transfer to, international recipients, gift-card routines, and records I may need later. Then I would test each relevant action separately. This is more reliable than assuming that because the app offers a feature, my personal workflow will transfer without adjustment.
Security checks can also add friction, especially when money is moving to a new recipient or across borders. I see that friction as useful when it makes me slow down, but it can be frustrating if I am trying to complete a time-sensitive payment. The best way to reduce stress is to avoid leaving unfamiliar transfers until the last minute and to review recipient details before I am under pressure.
For families, the decision may involve more than one person. If I am sending money to relatives or buying gift cards for them, I would make sure everyone understands which confirmation proves that the action was completed and who is responsible for checking receipt. Centralizing the transaction in my app does not remove the need for clear communication with the other person.
Who should choose it
I would recommend Inter Banking & Money Transfer to an Android user who wants a broad digital banking hub and expects to use more than ordinary account checking. It is particularly appealing if gift cards and international transfers are part of the same financial routine and I would rather not maintain separate specialist apps for every purpose. The free price also makes it easy to try without committing to a subscription.
I would be more cautious if I only need a minimal banking tool, rely heavily on branch support, or send international payments so frequently that a dedicated remittance service is central to my life. In those cases, a narrower alternative may offer a clearer workflow. I would also avoid making it my sole financial platform until I had tested the exact transactions I depend on most.
The Everyone content rating makes the app broadly approachable from an age-classification perspective, but that should not be confused with financial simplicity. Banking decisions still require adult judgment, careful review, and awareness of the recipient and amount. The interface may be accessible while the consequences of a mistaken transfer remain serious.
My recommendation after weighing the trade-offs
Inter Banking & Money Transfer is a convincing choice when convenience means bringing several money tasks together. Its combination of digital banking, gift cards, and international transfers gives it a practical identity beyond a basic account viewer. I appreciate that it can serve as a single starting point for everyday banking and occasional cross-border needs, provided I take time to verify each transaction.
My recommendation is to try it as a gradual addition rather than an instant replacement. Start with a familiar task, explore the transaction history and confirmation flow, then test the features that motivated the download. If the app genuinely reduces the number of services I use, the switch can be worthwhile. If I only need one narrow function, a specialist or simpler banking alternative may remain the better answer.
Banco Inter SA has built this app for a large digital audience, and its scale is reflected in the millions of ratings and more than 100 million installs. Still, my final decision would come down to fit: do I want one broad financial hub, and am I comfortable managing the details myself? For me, the answer is yes when gift cards or international transfers sit alongside normal banking. For someone who values maximum simplicity or personal support, I would recommend comparing alternatives before moving the whole routine.
Overall, I see Inter as a useful decision for people who want one mobile place for several financial workflows, not as a universal replacement for every banking or transfer service. Its best quality is the way it connects different needs. Its main limitation is that the wider scope may be unnecessary for a person with a very simple routine. Try it deliberately, keep the first transactions small, and let the way you actually manage money—not the size of the app—decide whether it earns a permanent place on your phone.
Pros
- Supports convenient transfers between linked bank accounts.
- Clear transaction records make it easier to track your money.
- Useful for managing payments without visiting a bank branch.
- May reduce transfer time compared with traditional banking methods.
- Designed to simplify routine banking tasks in one place.
Cons
- Transfer availability may depend on supported banks and regions.
- Some transactions may include service or processing fees.
- Identity verification can take time before full access is granted.
- Scheduled transfers may be delayed by weekends or holidays.
- A stable internet connection is required for most features.
FAQs for Inter Banking & Money Transfer
What is Inter Banking & Money Transfer, and what can I use it for?
Inter Banking & Money Transfer is a financial app designed to help users manage banking-related activities and send money between supported accounts or recipients. Depending on your country, bank, and account type, it may offer transfers, payment tracking, transaction history, and other money-management tools. Before downloading, check whether your bank and destination country are supported.
Is Inter Banking & Money Transfer safe to use for sending money?
The app should be used only through its official Android or iOS download page, and users should protect their account with a strong password, biometric authentication, and any available two-factor verification. Always confirm recipient details before approving a transfer. Avoid using public Wi-Fi for sensitive transactions, and contact the bank or provider immediately if you notice unfamiliar activity.
Are there fees, limits, or processing times for transfers?
Transfer costs and delivery times can vary according to the payment method, destination, currency, bank, and type of transaction. Some transfers may be free, while others can include service, exchange-rate, or receiving-bank fees. Daily or monthly limits may also apply. Review the final confirmation screen carefully, since it should show the amount, charges, and expected arrival time.
What information is required to create an account and make a transfer?
Registration commonly requires personal details such as your name, email address, phone number, and sometimes identity verification documents. To send money, you may need the recipient’s name, account number, bank details, routing information, or other country-specific identifiers. Enter every detail carefully, because an incorrect destination can delay the transfer or make recovery difficult.
What should I do if a transfer is delayed, rejected, or sent to the wrong person?
First, check the transaction status, notifications, and transfer history inside the app. A pending transfer may still be undergoing bank or compliance checks, while a rejected payment may require updated information or additional verification. If you entered incorrect recipient details, contact customer support and your bank immediately. Keep the transaction reference, date, amount, and recipient information available.

Inter Banking & Money Transfer
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via suporte.app@bancointer.com.br, visit https://www.inter.co, or review their https://www.bancointer.com.br/politica-de-privacidade/privacidade/.










